

Cash Advance Loan - CREDO
by Same Day Fin LLC
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
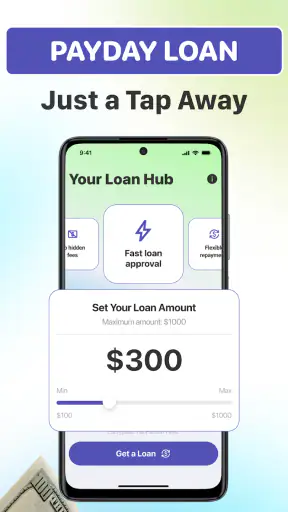
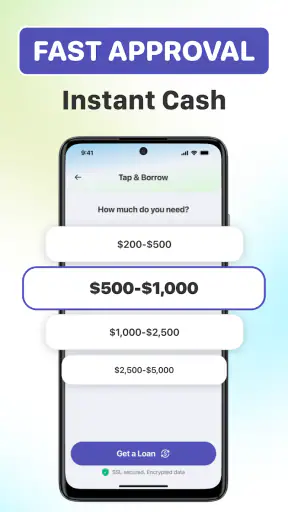
 Analysis by Getfullapps
When an unexpected bill lands between paydays, a cash-advance app can look appealing because it promises a faster route than a traditional loan application. I tested Cash Advance Loan - CREDO with that exact question in mind: does it make the borrowing process easier to understand, and does it give me enough control to make a careful decision? My answer is mixed. The app is clearly aimed at people who need to explore short-term borrowing from a phone, but convenience should not be confused with affordability.
CREDO is a free finance app from Same Day Fin LLC. Its store summary presents it as a place to find instant cash advances, including options described as requiring no credit check. That wording is important, but it should not be read as a promise that every applicant receives money, that every offer has the same terms, or that borrowing is cost-free. I would treat the app as a starting point for reviewing possible options, not as an automatic solution to a recurring income problem.
The app has reached over a hundred thousand installs and holds a 4.6 average from roughly twenty-one thousand ratings. Those figures suggest that many people have found the experience useful enough to rate, though popularity alone does not tell me whether a particular offer will suit my budget. The product is free to install and rated for Everyone, while the current release is version 0.11.2 and requires Android 7.0 or later.
How I judged CREDO before thinking about borrowing
I start by judging whether CREDO helps me make a deliberate choice, rather than treating quick access to borrowing as a benefit by itself. That means looking at how I would approach the app before entering sensitive details or considering an offer. From there, the key question is which checks and habits help keep a short-term decision grounded in my actual budget.
A finance app deserves a different kind of trust
With a casual utility, a little friction or an awkward screen is usually harmless. With a borrowing app, the stakes are higher. I pay attention to what the app asks me to enter, when it asks for it, how clearly the next step is explained, and whether I can stop before committing to anything. Those details matter more to me than a polished interface or a short promise about speed.
CREDO’s role is best understood as an access point for cash-advance possibilities rather than a replacement for a bank account, a budgeting tool, or a long-term credit product. That distinction changes how I use it. I would open it when I have a specific shortfall and a realistic repayment plan. I would not use it simply to see how much money I might be able to borrow, because browsing available credit can make an unaffordable option feel tempting.
The developer, Same Day Fin LLC, is visible as the company behind the app. That gives the product a clear identity, but it does not remove the need to inspect each screen and each offer carefully. In financial services, knowing who publishes an app is only one part of trust. The other part is understanding what happens to my information and what I am agreeing to at every stage.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What the no-credit-check message really means for a user
The phrase “no credit check” may be useful to someone worried about a thin or damaged credit history, but I would not treat it as a shortcut around normal eligibility checks. An application can still involve identity details, income information, banking information, or other requirements. Even when a traditional credit inquiry is not central to the process, the provider may use different information to decide whether an offer is available.
My practical advice is to slow down when the app moves from general information to a specific offer. Look for the amount you would repay, the timing, any fees, and whether the repayment method is clear. If the screen emphasizes the money arriving but makes the repayment side difficult to locate, I would stop and investigate before continuing. A fast application is not valuable if I cannot explain its total impact on my next paycheck.
Controls I would use before entering sensitive details
The most useful control is the ability to leave the process before submitting an application or accepting an offer. I would use that pause deliberately. First, I would write down the exact amount needed rather than entering the maximum available. Second, I would compare the expected repayment with my next income after rent, food, utilities, transport, and existing commitments. Third, I would take a screenshot or personal note of the terms shown before moving on, provided doing so does not expose private information.
I would also check the app’s permission prompts instead of approving everything automatically. A finance app may need certain information to operate, but the right question is whether each request is relevant to the action I am taking. If a permission feels unrelated, I would deny it and see whether the app still works. If refusing it blocks the entire process, that is a reason to reconsider how much access I am comfortable giving.
Account security is another point where I prefer visible choices over assumptions. I would use a unique password if the app requires an account, avoid sharing login details, and sign out on a shared phone. I would also review whether the app offers a way to update personal information or close an account. Those are simple steps, but they matter because financial information can remain sensitive long after a single advance has been repaid.
The moments when privacy deserves extra attention
The most data-sensitive part of the experience is not the initial download; it is the point where I begin an application. That is when I would expect requests for information connected to identity, income, contact details, or repayment. I would read the relevant disclosure instead of tapping through it, particularly if the screen asks me to consent to sharing information with other services or to receive communications.
I would be especially careful with bank-related access. If a connection to a financial account is offered, I would check what it is being used for, whether I can provide information another way, and whether the connection can later be removed. I would not connect an account merely to make the process feel faster. The small amount of time saved is not worth losing track of which service can view or use financial activity.
Notifications deserve the same thought. A reminder about an application or repayment can be helpful, but notifications may reveal financial activity on a lock screen. On a shared or frequently visible phone, I would adjust notification previews so that private details are not displayed openly. This is a user-side precaution rather than a claim about how CREDO handles notifications, but it is an easy way to reduce accidental exposure.
I would also avoid entering information while connected to an unsecured public network. That is sensible for any financial activity, and it becomes more important when an app handles identity or banking details. Using a trusted connection, keeping the operating system updated, and installing the app only from the official store are basic habits that reduce avoidable risk.
Where CREDO fits better than familiar alternatives
A traditional bank or credit union may be a better first stop for someone who already has an established relationship, because that person may be able to ask questions directly and compare a wider range of repayment structures. An employer-based advance program can also be more suitable when it clearly explains the connection to earned wages and does not encourage repeated borrowing. A credit card may offer more flexibility for a planned purchase, although it can become expensive when a balance rolls over.
CREDO’s advantage is the low barrier to exploring short-term options from a phone. That can be useful when a person has limited conventional credit access and needs to understand what might be available quickly. Its weakness is the same convenience: an app-based path can make a serious financial commitment feel like a routine checkout. I would choose it over a slower option only when I had already worked out the repayment plan and needed a convenient way to investigate an immediate gap.
For a small emergency that can be covered after the next confirmed paycheck, the app may be worth considering. For rent that is already unaffordable each month, an overdue debt being rolled into another debt, or a shortfall with no clear repayment date, I would look elsewhere for help. A creditor hardship arrangement, a local assistance program, or a conversation with a bank may take more effort, but those routes can address the underlying problem instead of postponing it.
A realistic use case: a bill before payday
Imagine I have a necessary car repair due before payday. I know the repair amount, I know when my income arrives, and I have checked that repaying an advance would still leave enough for essentials. In that situation, I could open CREDO, review the available path, and stop if the repayment terms do not match my calculation. The important part is that the repair is specific and the repayment source is already known.
Now change the situation: I am short every month and want an advance to cover groceries, then plan to use the next advance for utilities. I would not recommend relying on CREDO in that pattern. Even a smooth application process cannot turn an ongoing deficit into a temporary one. The app might help me investigate an immediate option, but it should not become part of my regular income.
A less obvious tip is to calculate the “after repayment” budget before applying, not after receiving an offer. I would list the next pay date, fixed bills, essential spending, and any automatic withdrawals. Then I would subtract the possible repayment. If the remaining amount is already too tight, I would not use the app to search for a larger advance. That simple order of operations protects me from letting the available amount dictate my budget.
What I would check on every offer screen
I would look for the total amount to repay rather than focusing on the amount deposited. I would identify the due date or repayment schedule, confirm whether repayment is automatic, and check what happens if the date arrives when the account balance is insufficient. I would also look for any optional service, recurring charge, or communication consent that is presented alongside the borrowing decision.
If the app routes me toward another provider, I would treat that transition as a new decision rather than assuming the same terms apply. I would read the provider name, review its disclosures, and confirm that I am still comfortable sharing the requested information. This is one of the most important distinctions between using a finance app as a discovery tool and treating it as the lender itself.
I would never pay an upfront fee simply because a message suggests it is necessary to unlock an advance. I would also be cautious if I felt pressured to act immediately or if the repayment details were hidden behind several screens. Urgency can be real when a bill is due, but pressure is not a substitute for clear terms.
Everyday usability and the friction I would accept
The free price makes CREDO easy to try, and the Everyone rating means the app is presented for a broad audience. Still, finance apps should not be judged only by how quickly they open. I care about whether the language is understandable, whether buttons distinguish information from consent, and whether I can go back without accidentally submitting something.
Version 0.11.2 indicates that the app is still at a relatively early version stage, so I would keep my expectations practical. I would update it through the official store, check the developer name before installing an update, and avoid using an outdated build for sensitive activity. I would also review the app after an update because permission prompts, account screens, or consent wording can change as a finance product develops.
One useful workflow is to separate research from action. I would first read the available information without entering unnecessary details. Then I would close the app and compare the possible repayment with alternatives. Only after that pause would I return to complete an application. This reduces the chance that a moment of stress turns into an impulsive commitment.
Who should use it and who should skip it
I see CREDO as a reasonable option for an adult who needs to investigate a short-term cash advance, understands that eligibility and terms can vary, and has a confirmed way to repay. It may also appeal to someone who wants to explore borrowing from a mobile device rather than visiting a branch. The app’s straightforward purpose makes it easier to focus on one immediate financial question.
I would skip it if I am looking for a guaranteed approval, a free source of money, or a way to avoid all financial checks. I would also avoid it if I cannot comfortably explain the repayment date, if my account balance is already unstable, or if I am considering an advance for a nonessential purchase. People who prefer face-to-face guidance may be better served by a bank, credit union, or nonprofit adviser.
Parents should remember that an Everyone content rating describes general suitability of the app’s content, not suitability for taking on debt. A young person can still make a serious financial decision inside a broadly rated finance app. I would focus on financial responsibility and consent rather than treating the age label as a recommendation to borrow.
My cautious verdict after weighing convenience against control
CREDO is most useful when it helps me examine a specific short-term need without rushing me into it. The free access, mobile format, and focus on cash advances make it convenient to explore. Its strong average rating and growing install base show that it has attracted substantial user attention, but neither tells me whether an individual offer is affordable or whether the app is right for my circumstances.
My recommendation is conditional. I would use Cash Advance Loan - CREDO as a research and application starting point only after preparing a repayment budget, checking every disclosure, limiting permissions to what feels necessary, and confirming who is responsible for the final offer. I would leave immediately if the terms were unclear, the pressure felt excessive, or the repayment would create another shortfall.
In the end, the app’s real value depends less on the promise of speed than on my willingness to pause. For a one-time emergency with a dependable repayment plan, it may be a practical option to investigate. For repeated borrowing or an income problem that will still exist next month, I would choose a solution that addresses the budget itself. That is the boundary I would keep firmly in place.
Pros
- Simple application process with clear loan details.
- Fast eligibility checks can save time for urgent needs.
- Useful repayment information helps with budgeting.
- Mobile access makes managing the loan convenient.
- Suitable for users seeking a short-term borrowing option.
Cons
- Interest and additional fees may make borrowing expensive.
- Approval and loan terms can vary by applicant.
- Late payments may lead to penalties or added charges.
- Short repayment periods can create financial pressure.
- Availability may depend on location and eligibility requirements.
FAQs for Cash Advance Loan - CREDO
What is Cash Advance Loan - CREDO, and how does it work?
Cash Advance Loan - CREDO is a financial app designed to help eligible users request a short-term cash advance through their mobile device. After creating an account, you generally provide personal and financial information, choose an available amount, and submit an application for review. Approval, loan terms, fees, and repayment dates depend on CREDO’s assessment and the conditions shown before acceptance.
Who can apply for a loan through Cash Advance Loan - CREDO?
Eligibility depends on factors such as your age, country or region, identity information, income, banking details, credit profile, and applicable legal requirements. Installing the app does not guarantee approval, and requirements may change over time. Before applying, carefully check the eligibility section and make sure all information entered is accurate, complete, and consistent with your official documents.
How much does a Cash Advance Loan - CREDO loan cost?
The total cost can include interest, service charges, origination fees, late-payment penalties, or other applicable expenses. The exact amount varies according to the loan offer, repayment period, and your individual profile. Review the annual percentage rate, total repayment amount, due date, and every additional fee in the agreement before accepting. Do not rely only on the advertised borrowing amount.
How and when must the loan be repaid?
Repayment conditions are presented with the specific offer and may require a one-time payment or scheduled installments, depending on the product available to you. Make sure the linked payment method or bank account has sufficient funds before the due date. Missing a payment may result in extra charges, collection activity, or negative effects on your financial record, so contact official support promptly if repayment problems arise.
Is Cash Advance Loan - CREDO safe to use?
The app may use security measures to protect account and application data, but users should still review its privacy policy, permissions, and official developer information before submitting sensitive details. Download only from a trusted app store or verified source, avoid sharing passwords or verification codes, and confirm that the lender and terms comply with local regulations. A legitimate app should clearly explain data use, fees, support, and repayment obligations.











